
In a significant push to promote industrial investment and streamline corporate restructuring, the Odisha government has announced substantial remissions and reductions in stamp duty for company mergers, amalgamations, and demergers.
An official order in this regard was issued today by the Revenue and Disaster Management Department. Exercising powers conferred under Section 9(1)(a) of the Indian Stamp Act, 1899, the state government modified its previous order dated March 24, 2023, to introduce this industry-friendly tax relief.
Under the new guidelines, instruments executed for the reconstruction, amalgamation, demerger, or arrangement of companies—sanctioned by the National Company Law Tribunal (NCLT) or other competent authorities under Sections 230 to 232 of the Companies Act, 2013—will receive targeted duty exemptions based on the scale of the enterprise:
- 100% Waiver for MSMEs: If the resulting, transferee, or surviving entity qualifies as a Micro, Small, or Medium Enterprise (MSME) under the MSME Development Act, 2006, it will receive a complete 100 per cent stamp duty exemption. To avail of this benefit, approval from the General Manager of the District Industries Centre (DIC), countersigned by the Director of Industries, will be mandatory.
- ₹50 Crore Cap for Large Industries: For large industries and corporate entities not falling under the MSME category, the maximum chargeable stamp duty has been capped at ₹50 crore. These cases will be evaluated on a case-to-case basis by the High Level Clearance Authority (HLCA)—constituted under the Odisha Industries (Facilitation) Act, 2004, and chaired by the Chief Minister—following due diligence and examination by the concerned departments.
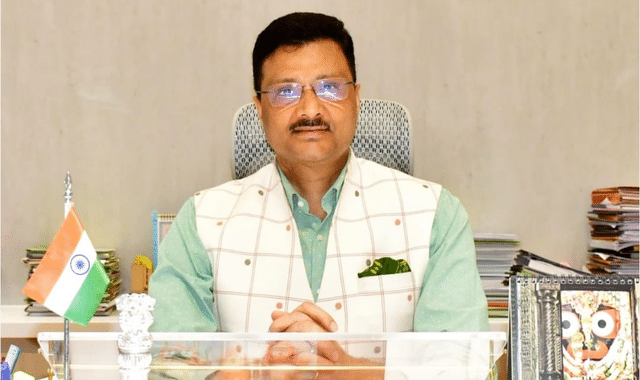
Dr. Arabinda Kumar Padhee, Additional Chief Secretary of the Revenue and Disaster Management Department, stated that this reform will significantly bolster industrial expansion, improve the ease of doing business in Odisha, and make corporate restructuring processes much smoother for enterprises across the state.