
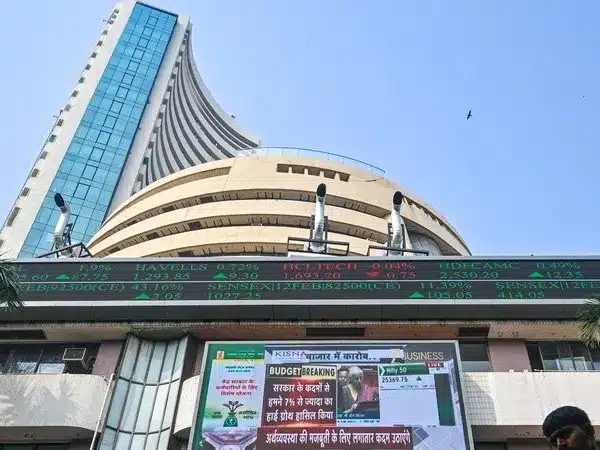
Indian equity benchmark indices staged a sharp intraday recovery on Monday, 9 November 2026, successfully erasing earlier losses to close in positive territory. Driven by robust buying in public sector banks and pharmaceutical heavyweights, the Sensex advanced 107 points to finish at 81,106.48, while the Nifty 50 successfully reclaimed the crucial 25,000 threshold.
Despite a volatile trading session and a negative market breadth, broader indices outperformed frontline benchmarks, supported by easing market volatility and selective institutional buying.
Sectoral Highlights: PSU Banks Rally & IT Weakness
Sectoral performance remained polarized as financial and defensive stocks countered heavy selling pressure in technology counters:
- Banking & PSU Surge: The Nifty PSU Bank index led sectoral gains with an impressive 3.61% surge, hitting multi-month highs. Heavyweights such as State Bank of India (SBI), Punjab National Bank (PNB), and Bank of Baroda witnessed aggressive buying.
- Pharma & Healthcare Rally: Strong Q2 earnings reports—most notably from Divi’s Laboratories hitting all-time highs following a 64% surge in net profit—propelled the Nifty Pharma and Healthcare indices up by over 1.5%.
- IT & Metal Drag: The Nifty IT index faced severe selling pressure, sliding 1.55% due to weakness in tech giants like Infosys, TCS, and Tech Mahindra. Metals also traded lower, weighed down by profit-booking in Tata Steel following cautious broker notes regarding its UK operations.
Index Movers & Broader Market Performance
- Top Nifty Gainers: SBI (+2.55%), Larsen & Toubro (+1.87%), HDFC Bank (+1.74%), and Trent (+1.62%).
- Top Nifty Losers: Tata Steel (-2.79% post-Q2 results), HCLTech (-2.53%), UltraTech Cement (-2.39%), and Infosys (-1.68%).
- Broader Markets & Volatility: The Nifty Midcap 100 gained 0.20%, and the Smallcap 100 advanced 0.05%. Meanwhile, the India VIX dropped 5.05% to settle at 17.50, reflecting tempered near-term market anxiety.